

👉 Turns out, it does, sort of… Whether fund managers who outperform once are more likely to do so again is an important question for fund selection.
👉 In the early days of scholarly research on the topic, evidence suggested that they do. However, for vintages post 2000, there is little evidence of performance persistence in PE.
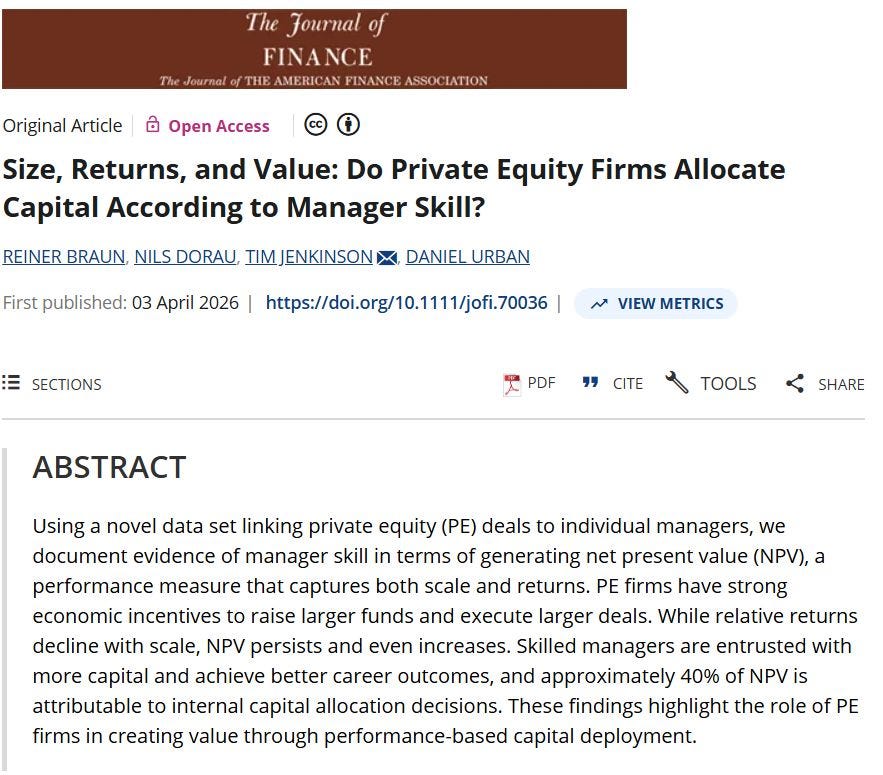
👉 Historically, research on the topic has focused on performance relative to peers as measured by PME or IRR. But in an interesting new paper, published just a few days ago in The Journal of Finance, the authors find that while relative returns decline with scale, NPV—a measure that captures both scale and returns—persists and even increases.
👉 This research suggests that GPs with good performance are able to raise larger funds and do bigger deals. This erodes outperformance as measured with traditional metrics, but allows for a persistence NPV. It also, of course, generates higher fees for the GP.
👉 Another interesting finding in this paper is that this NPV persistence is not only observable at the level of the GP but also at the level of the individual investment professional, with the career benefits one would expect.
👉 To me, this paper provides solid academic evidence for something many investors will have already suspected. It also points rather directly to an interesting question:
▶️ would you rather a GP raises larger funds and does larger deals, eroding gross IRR/ PME outperformance,
▶️ or would you prefer a hard cap at a smaller fund size but with a higher fee structure, eroding net return KPIs but allowing headline returns to persist?
👉 There is much more to this paper and for those inclined, I would suggest taking the time to read it. It is also available for free on an open-access basis: Size, Returns, and Value: Do Private Equity Firms Allocate Capital According to Manager Skill?
Happy to share the link for anyone interested.
Note: All errors are my own