

Despite its rapid growth over the last decade, private equity remains smaller by AuM than Blackrock. Private debt and infrastructure are nowhere close.
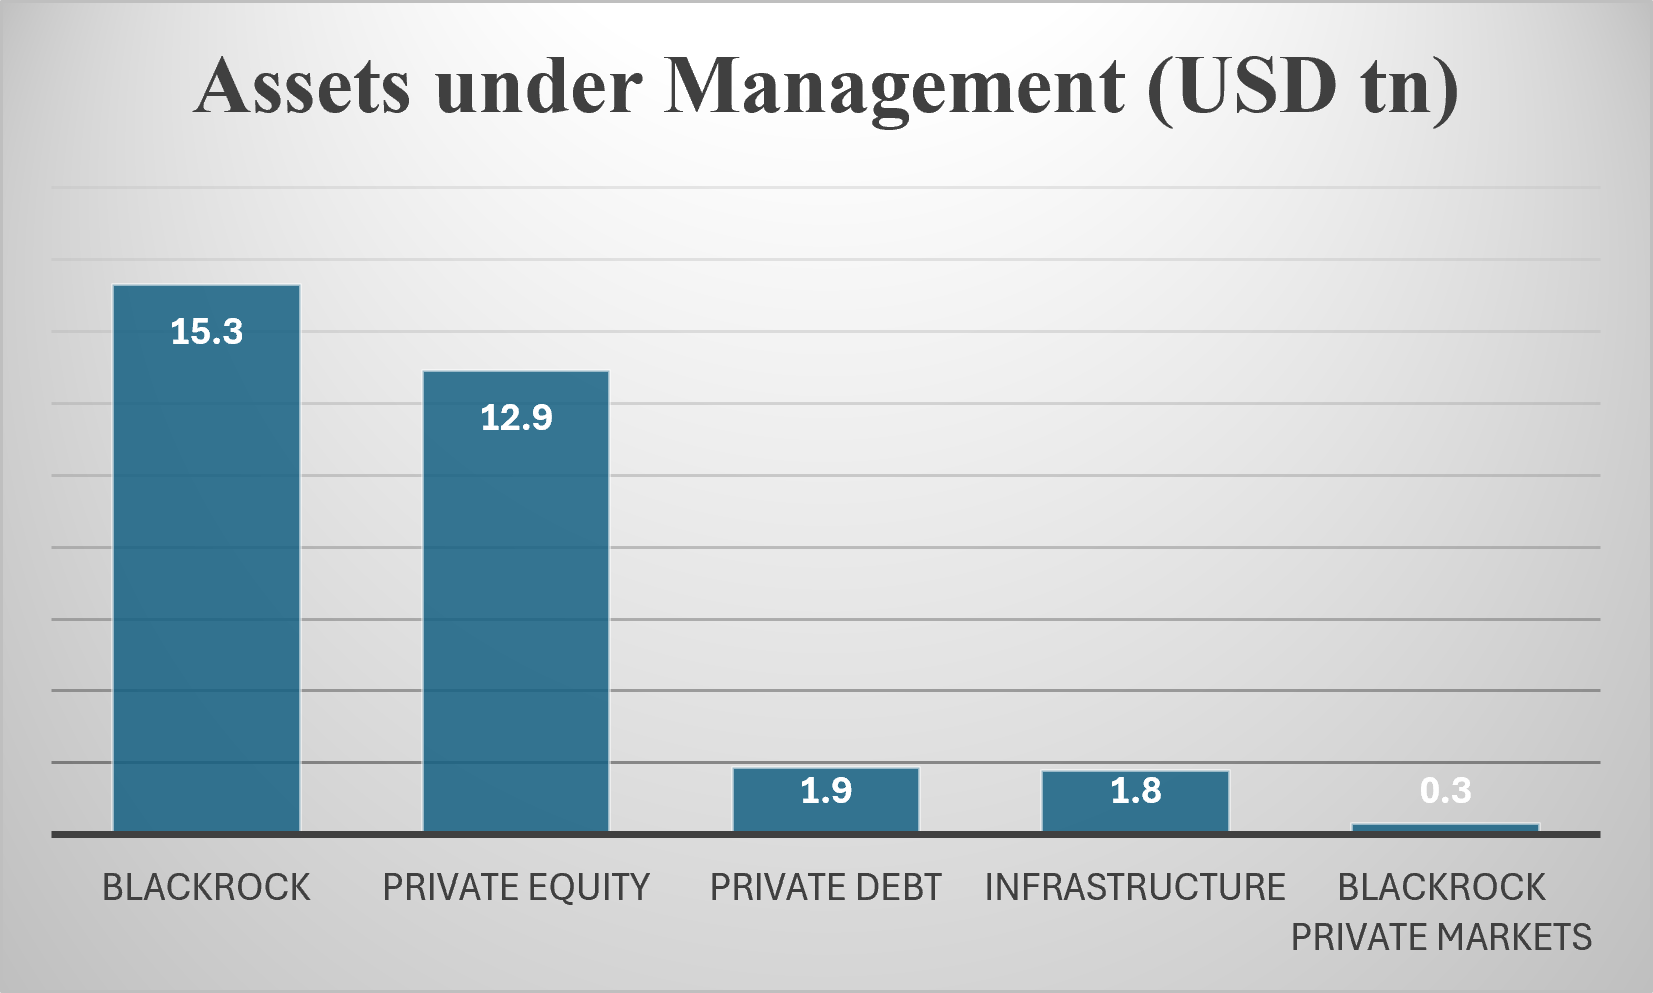
A few things stand out to me here:
1️⃣ Firstly, it highlights how small private markets still are in comparison to the wider investment industry.
➡️ In my view, it's pretty much impossible to say how big private markets could get.
➡️For private equity and private credit any corporate could theoretically become a relevant target at the right price: From small entrepreneur-run businesses selling into roll-up platforms to listed giants being taken private, the potential universe is practically uncapped.
This is limited in practice, but a larger and more diverse private equity industry could unlock parts of the universe.
➡️And notionally the infrastructure market could include all roads, ports, airports, hospitals and energy assets.
2️⃣ Private markets make up c. USD 330 billion of Blackrock’s AuM, representing c. 2% of the total USD 15.3 trillion.
➡️ Despite this, private markets constitute 11% of the Blackrock’s base fee and securities lending revenue.
➡️ No surprises here, but it does underline why despite recent noise in the BDC space, large asset managers are keen to push further into the private markets.
Data from: Blackrock Q2 2026 earnings release, Preqin as at December 2025 (extracted July 2026); all errors are my own.